Research Overview
My recent work studies the joint dynamics of the best bid and ask prices with Hawkes processes. With Kiseop Lee, I developed a spread-gated Hawkes-flocking model of the four types of best-quote moves. Spread-narrowing moves are switched off when the spread is at its one-tick minimum, and a cross-side excitation term, whose activation depends on the prevailing spread, links the two sides of the book. On limit order book data for INTC and MSFT, the model without the cross-side term is rejected, and the full model fits substantially better. As an application, we derive the closed-form optimal size of a limit order placed at the best or second-best quote.
In related work, I study how the definition of a price-change event affects Hawkes estimates in the consolidated US quote feed. Hawkes fits to this feed typically find a sub-millisecond kernel component and a branching ratio near criticality. I show that in large-tick stocks the sub-millisecond component comes from how the feed is constructed: half of NBBO changes are locks or depleted quotes that resolve within a millisecond, and the model reads them as excitation. Defining an event as a mid-price level that persists for one millisecond removes the component.
Building on these, I am working on when to execute an order given real-time forecasts of price direction, and on how stable directional dependence in mid-price moves is from day to day, and whether its variation can be predicted. A second line of work, partly with students, develops online monitoring of covariance structure in high-dimensional financial return panels, with calibrated false-alarm control. I also work with students on forecasting energy prices with statistical and deep learning models.
Publications
-
Optimal execution with liquidity risk in a diffusive order book marketInternational Journal of Financial Engineering, 10(03), 2350018, 2023.
-
Optimal placement of a small order in a diffusive limit order bookHigh Frequency, 1, 87–116, 2018.
Submitted and under review
-
Event definition and the branching ratio: Hawkes estimates of price-change clustering in the consolidated quote feedSubmitted, 2026.
-
A spread-gated Hawkes-flocking model for best bid and ask dynamics, with an application to limit order placementUnder review, 2026.
Work in progress
-
How stable is directional dependence in mid-price moves? Evidence from a multi-timescale Hawkes model
-
Evaluating hybrid deep learning architectures for day-ahead electricity price forecasting in the German spot market
Recent Talks
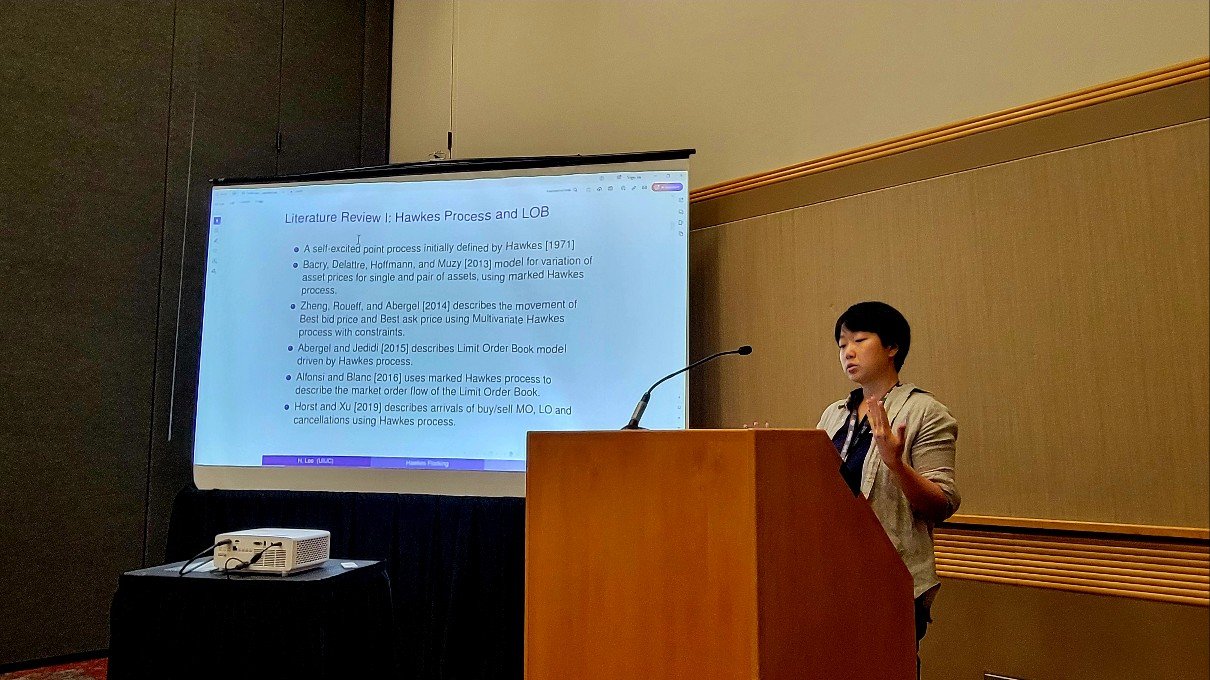
- EcoSta 2026 (online) Aug 2026 Algorithmic trading in a Hawkes flocking LOB model
- JSM Annual Meeting, Portland, OR Aug 2024 Algorithmic trading in a Hawkes flocking LOB model
- Computational Finance Seminar, Purdue University Feb 2024 Algorithmic trading in a Hawkes flocking LOB model
- SIAM Conference on Financial Mathematics & Engineering, Philadelphia, PA Jun 2023 Algorithmic trading in a Hawkes flocking LOB model
- Computational Finance Seminar, Purdue University Sep 2022 Optimal execution with liquidity risk in a diffusive order book market